The fintech startup guide to international expansion
See how Findigs, Accompany Health, Veramatic and Podifi built their teams.
Real teams, real results, from faster hiring to lasting retention.
Quick look:
| International expansion gives a fintech startup new customers, wider talent pools, and protection from a downturn in any one market. A practical path runs through ten steps: research target countries, plan an offshore team, pick a hiring model, stay compliant, set up tools, build a cross-cultural team, onboard well, track results, manage the budget, and keep long-term partners close. Regulation and data protection rules differ by country, so check them before you hire or launch. |
|---|
The rise of fintech startups
Fintech startups have reshaped financial services by using tech to make them faster and more accessible. Fintechs have reduced the need for brick-and-mortar banks and made finance more inclusive.
Fintech can cover a broad range of services, including:
- Digital banking: Services like online banks and digital wallets (e.g., Revolut, N26)
- Payment solutions: Fast, digital payments via mobile apps (e.g., PayPal, Stripe)
- Lending platforms: Online loan marketplaces and P2P lending
- Cryptocurrency and blockchain: Decentralized finance services
Fintech is no longer a niche market. It is now a key driver of the economy, and fintech companies handle a large share of everyday transactions. Consumers increasingly rely on mobile payments, online loans, and digital currencies, making fintech one of the most exciting and disruptive sectors in the business world.
As the sector continues to grow, fintech startups face an inevitable challenge: how to scale globally.
Why international expansion is key for fintech startups
While many fintech startups begin by focusing on a local market, the real growth potential lies in international expansion. Global markets offer opportunities to access new customers, tap into different talent pools, and diversify business risks. Here's why fintech startups should prioritize international expansion:
- Access to global talent: Offshore hiring lets fintech companies build skilled teams in more places, which is critical for staying competitive
- Larger customer base: Expanding into new regions allows startups to reach a broader range of consumers and business clients
- Regulatory diversity: International expansion forces startups to adapt to new regulations, making them more resilient and adaptable over time
- Risk diversification: Operating in multiple regions can safeguard businesses from local economic downturns or market disruptions
For budding fintech companies with an ambitious vision, international expansion is the logical next step.
Step-by-step guide to international expansion
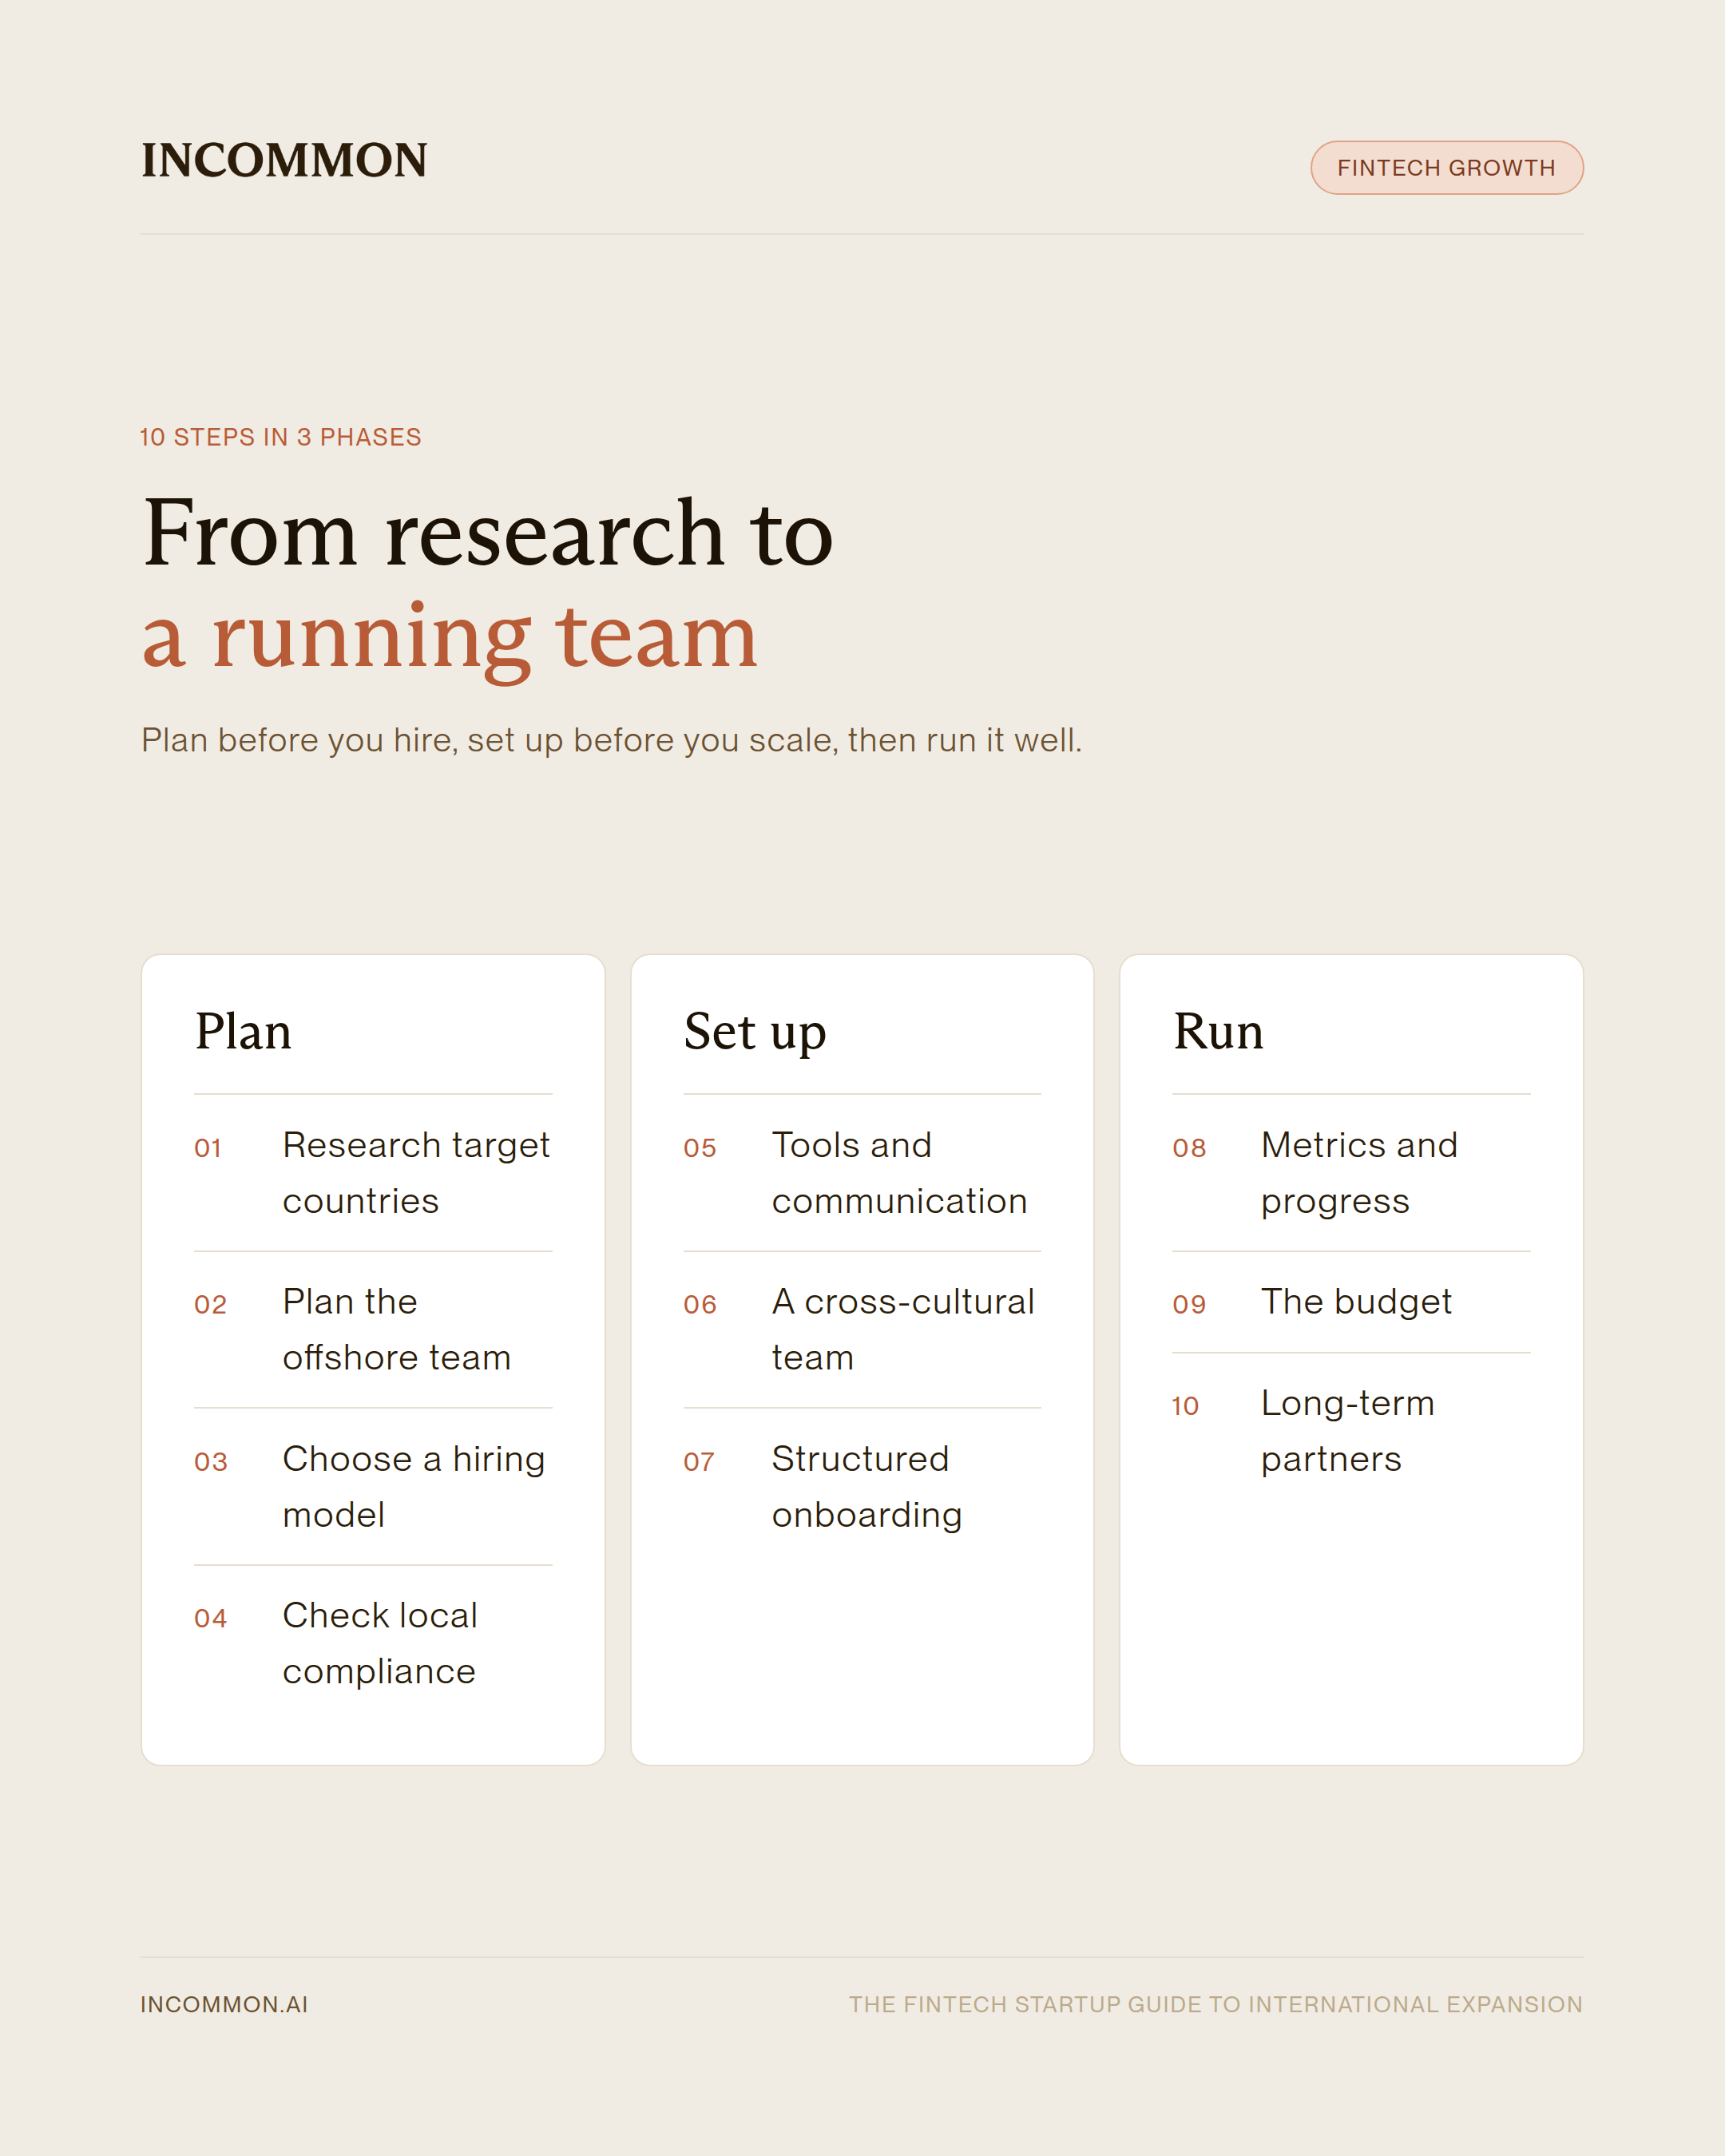
1. Research your target countries
Thorough research tells you each market's financial regulations, economic climate, and competition:
- Understand regulatory environments: Fintech regulations vary by country. Some require special licenses or certifications
- Analyze the economic climate: Look for markets with growing demand for financial technology, such as emerging economies or underbanked regions
- Identify competitors and opportunities: Assess competitors and see if there's a gap for your unique services
- Consider consumer preferences: Understand how locals prefer to interact with financial technology and tailor your product accordingly
2. Plan your offshore team
An offshore team can handle customer support, development, and other key roles, which adds flexibility as you grow:
- Identify roles for offshore staff: Engineering, customer support, and compliance are common offshore roles for fintech
- Choose the right offshore location: Consider countries with skilled talent pools, such as India for tech or the Philippines for customer support
- Understand time zones and overlap: Aim for a few hours of overlap each day so the teams can work together in real time
- Set clear job descriptions: Be specific about expectations and performance standards
3. Choose the right hiring model
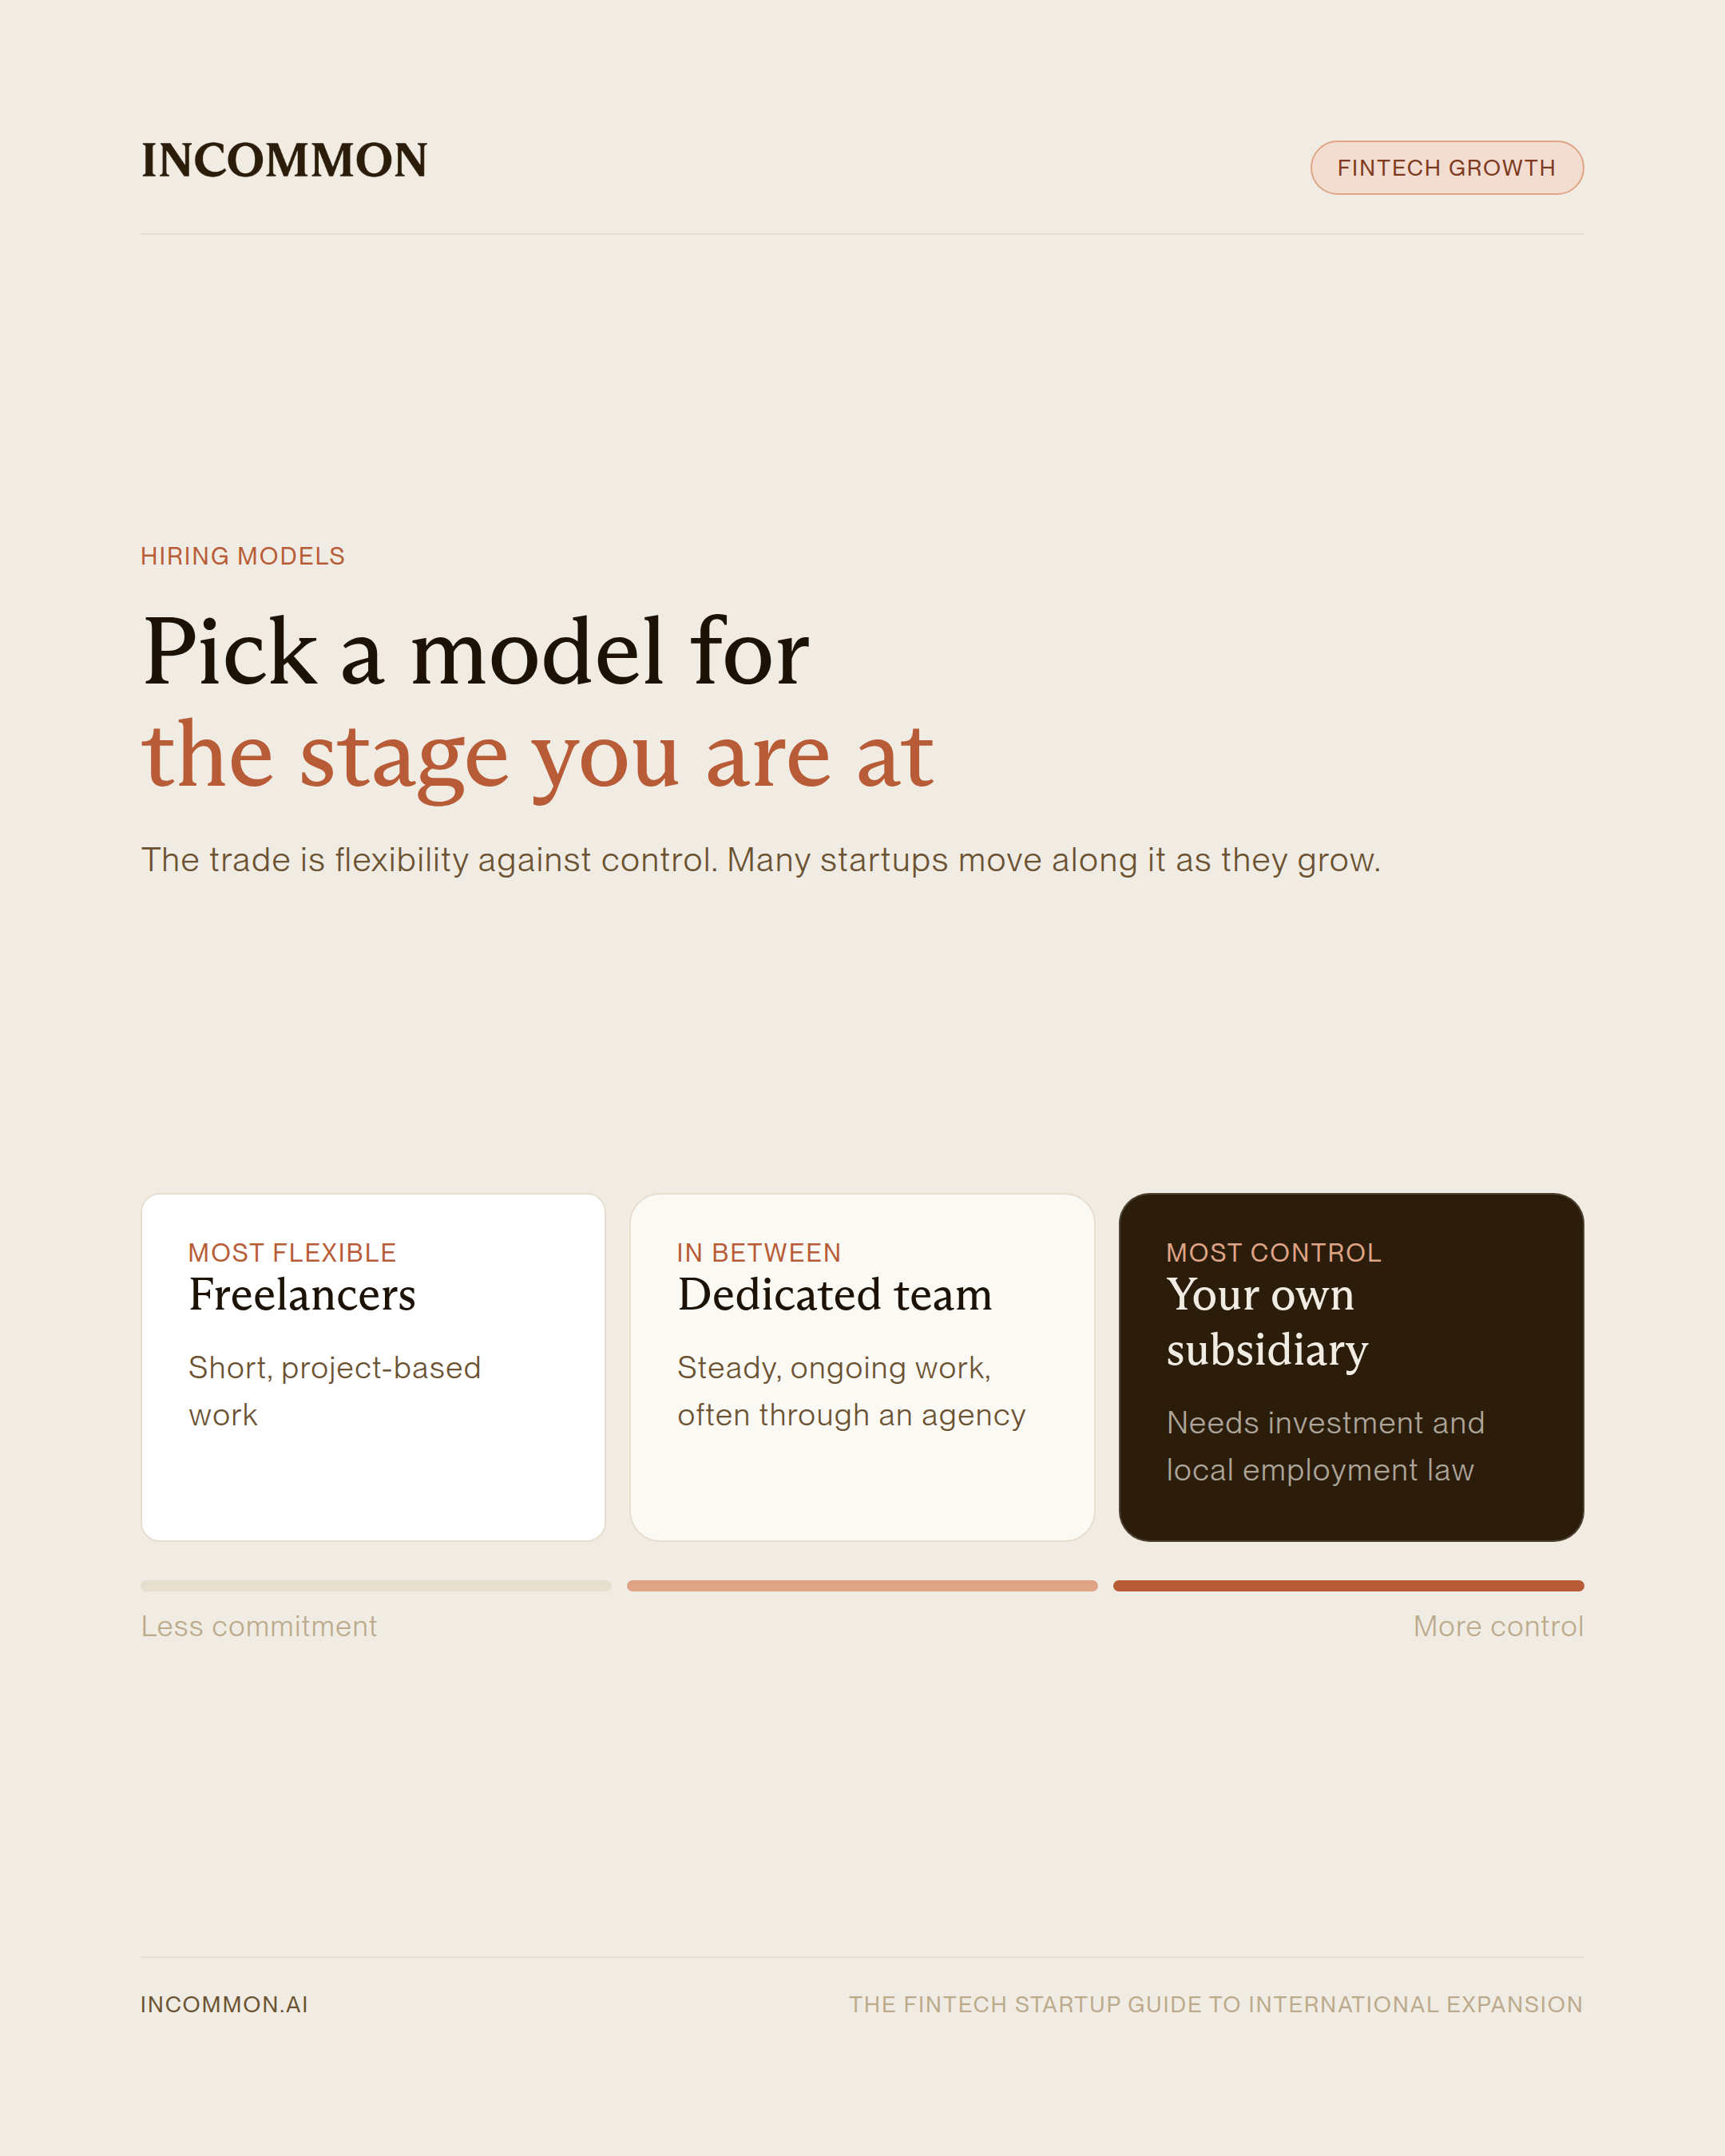
Various hiring models can suit different stages of business growth:
- Freelancers: Useful for project-based tasks or when you need flexible, short-term support
- Dedicated offshore team: Typically hired through an offshore agency; this is ideal for consistent, ongoing work
- Employer of record (EOR): An EOR employs people for you in a country where you have no entity, and handles payroll, taxes, and local compliance. It is a common way to make your first hires abroad, and our guide to EOR vs your own India entity explains when it fits
- Subsidiary office: Setting up your own subsidiary office can provide more control but requires investment and knowledge of local employment laws
4. Ensure compliance with local regulations
Compliance is crucial in the fintech space, where privacy and data protection laws vary:
- Understand data protection laws: Many countries enforce strict data protection, such as GDPR in Europe and the Digital Personal Data Protection (DPDP) Act in India. Ensure compliance from the start
- Follow employment laws: Learn about local hiring practices, wages, and benefits to avoid any legal complications
- Obtain required licenses and permits: Each country sets its own requirements for operating as a fintech provider
5. Set up technology and communication tools
Having the right tech infrastructure will keep the team aligned and boost productivity:
- Project management tools: Use tools like Asana, Jira, or Monday to track progress and manage tasks
- Communication platforms: Slack, Zoom, and Microsoft Teams can bridge the distance for real-time updates
- Data security measures: Implement secure data handling practices with tools like VPNs, encrypted communication, and secure cloud storage
6. Develop a cross-cultural team structure
A unified team culture builds morale and productivity:
- Host regular team meetings: Weekly or monthly check-ins can keep the team aligned and address issues early
- Offer cultural sensitivity training: Bridging cultural gaps can prevent misunderstandings
- Set up clear communication guidelines: Specify expectations around response times, work hours, and feedback mechanisms
7. Create an effective onboarding process
For offshore employees, a structured onboarding program helps build knowledge and confidence:
- Introduce company values and goals: Help them feel part of the larger mission from day one
- Assign a buddy or mentor: Pair new hires with a senior team member to support them during the transition
- Provide comprehensive training materials: Use a mix of recorded videos, written documentation, and live Q&A sessions
8. Define success metrics and track progress
Regular assessments help keep your offshore team aligned with company goals:
- Set key performance indicators (KPIs): Define KPIs that align with your business objectives, such as customer satisfaction or product development timelines
- Use productivity tracking tools: Track the team's output using tools like Trello, ClickUp, or Hubstaff
- Request regular feedback: Keep communication open so you can adjust processes and support before problems grow
9. Manage the budget
An offshore team needs an accurate budget and a plan from the start:
- Evaluate initial setup costs: Calculate the costs associated with recruiting, onboarding, and technology setup
- Monitor ongoing expenses: Include salaries, benefits, taxes, and other administrative costs
- Review cost against quality: Periodically assess whether budget pressure is affecting service quality
10. Build long-term partnerships with providers
If you're working with an offshore agency or third-party providers, a strong relationship makes the partnership work better for both sides:
- Regular check-ins and reviews: Maintain regular touchpoints to discuss progress and any concerns
- Transparent communication: Share business goals and involve them in decision-making when possible
- Offer long-term contracts: This can incentivize providers to prioritize your work and assign skilled people to it
If India is on your expansion list, this is how we help teams get started there.
Everything you need to build and run your India GCC.
Entity, hiring, workspace and ongoing operations under one agreement.
How AI makes international hiring easier and faster
AI-driven recruitment tools and platforms can make hiring offshore employees faster and more efficient:
- Automated candidate screening: AI can help businesses sort through thousands of resumes quickly, so recruiters spend their time on the most qualified candidates
- Language assessment: AI-powered tools can help test a candidate's language skills, which matters when hiring across borders
- Streamlined onboarding: AI can automate onboarding processes, making it easier for new offshore employees to get up to speed, no matter where they're located
By incorporating AI into the hiring process, fintech companies can reduce the time it takes to find the right candidates. This technology allows businesses to scale their operations efficiently while maintaining high hiring standards. In a fast-moving industry like fintech, ignoring AI in international hiring would be a missed opportunity.
Use these tools with care, though. AI used in hiring is now regulated in some places. New York City requires bias audits of automated hiring tools, and the European Union's AI Act treats recruitment AI as high-risk. Check the rules in every country where you hire, and keep a person responsible for the final decision.
What to watch as you expand
Fintech keeps changing, and so do the rules around it. Three trends shape where and how fintech startups expand:
- Increased competition: More fintech startups are entering the market, making it more challenging for smaller players to stand out
- Expansion into emerging markets: As fintech adoption grows in regions like Africa, Latin America, and Southeast Asia, startups will need to expand into these areas to remain competitive
- AI in daily operations: AI is now widely used in fraud detection, credit decisions, and customer support, and regulators are paying closer attention to how it is used
International expansion is now a necessity for ambitious fintech startups that want to succeed on a global scale.
Frequently asked questions
Why should fintech startups expand internationally?
International expansion opens new customer markets, gives access to wider talent pools, and spreads risk across regions so a downturn in one market does not stall the business.
What should a fintech startup research before entering a new country?
Research the country's financial regulations and licensing rules, its economic climate and demand for financial technology, the competition, and how local consumers prefer to use financial services.
Which roles do fintech startups usually place in offshore teams?
Engineering, customer support, and compliance are common offshore roles for fintech companies. India is a common choice for tech roles and the Philippines for customer support.
What hiring models can a fintech startup use abroad?
Freelancers suit short, project-based work. A dedicated offshore team, often hired through an agency, suits consistent ongoing work. An employer of record lets you hire in a country without an entity. A subsidiary office gives the most control but needs investment and knowledge of local employment law.
What compliance issues matter most for fintech expansion?
Data protection laws such as GDPR in Europe and India's DPDP Act, local employment laws on wages and benefits, and the licenses and permits each country requires to offer financial services.
How can AI help with international hiring?
AI tools can screen large volumes of resumes, test language skills, and automate parts of onboarding, which shortens the time it takes to find and ramp up the right people. Hiring AI is regulated in some places, so check the local rules first.
Written by
CEO, InCommon
Piyush Kedia is the CEO of InCommon, a talent infrastructure company that helps US and global enterprises set up and scale Global Capability Centers (GCCs) in India. He works with founders, CTOs, and heads of talent to design smaller, AI native GCC teams that focus on judgment work, not just headcount, so India offices stay senior, stable, and production ready. Before InCommon, Piyush built Blue Vector into a 50 person creative agency serving brands such as Trump Towers, Audi, and Porsche, giving him a front row view of how high performing teams are hired, managed, and grown.